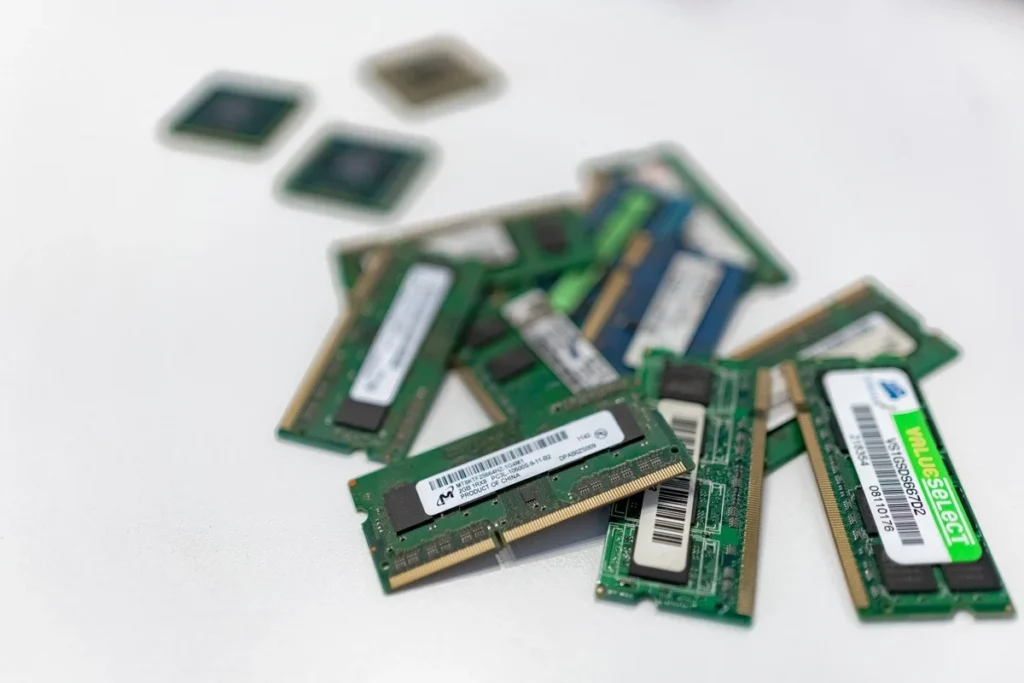
In a significant development poised to reshape the global memory landscape, ChangXin Memory Technologies (CXMT), a leading Chinese memory manufacturer, has announced the commencement of mass production utilizing its fifth-generation DRAM manufacturing process. This breakthrough, which reportedly delivers approximately double the memory density of its preceding generation, marks a pivotal moment for China’s domestic semiconductor industry, signaling a concerted push towards greater self-sufficiency and a strategic move into more advanced segments of the memory market. The announcement comes at a time when the world grapples with a persistent memory crisis, exacerbated by unprecedented demand from artificial intelligence (AI) infrastructure, creating a unique window of opportunity for emerging players like CXMT.
A Technical Leap Forward: High-k Metal Gate Technology for Enhanced Density
At the heart of CXMT’s latest achievement is the successful implementation of a high-k dielectric metal-gate process, meticulously adapted for DRAM manufacturing. This technology is not entirely new to the broader semiconductor industry, having been widely adopted in advanced logic and other memory types by established international manufacturers for years. Its integration into CXMT’s DRAM production, however, represents a crucial step in narrowing the technological gap with global leaders such as Samsung, SK Hynix, and Micron.
High-k (high dielectric constant) materials, when used in conjunction with metal gates, replace conventional silicon dioxide gate dielectrics. This change allows for a thinner physical gate dielectric while maintaining the same effective capacitance, thereby reducing leakage currents, improving transistor performance, and enabling greater miniaturization. For DRAM, this translates directly into higher memory density – meaning more storage capacity can be packed into the same silicon area. The reported doubling of memory density per unit of silicon is a substantial gain, offering the potential for more cost-effective production if CXMT can maintain high manufacturing yields at scale.
To demonstrate the efficacy of this new process, CXMT has showcased two 24GB LPDDR5X memory products. LPDDR5X (Low Power Double Data Rate 5X) is a high-performance, low-power memory standard primarily targeted at demanding applications such as smartphones, premium tablets, and other high-end portable computing devices. The ability to produce competitive LPDDR5X is particularly noteworthy because it signifies CXMT’s progression beyond basic commodity DRAM into a segment requiring higher bandwidth, lower power consumption, and more sophisticated design and manufacturing capabilities. This move positions CXMT as a serious contender in a market previously dominated by a handful of international giants.
The Global Memory Crisis and the AI Imperative
The timing of CXMT’s announcement is strategically significant, coinciding with what many industry analysts describe as a profound global memory crisis. This crisis is multifaceted, stemming from a confluence of factors including pandemic-induced supply chain disruptions, geopolitical tensions, and an insatiable demand for memory driven by the exponential growth of artificial intelligence.
AI, in particular, has emerged as a voracious consumer of high-performance memory. The development and deployment of large language models, advanced machine learning algorithms, and complex AI accelerators require enormous quantities of specialized memory, notably High Bandwidth Memory (HBM). HBM, with its stacked die architecture and high data transfer rates, is crucial for feeding the processing power of AI GPUs. The surging demand for HBM has prompted major memory manufacturers to prioritize investment and production capacity towards these high-margin, cutting-edge products, creating a supply squeeze and driving up prices across the entire memory market.
Industry projections highlight the scale of this demand. Analysts at Gartner, for instance, estimate that global AI chip revenue could reach over $53 billion in 2023, representing a 20.9% increase from 2022, with memory being a critical component. The global DRAM market, valued at approximately $90 billion in 2022, is projected to grow substantially, with AI-related segments expanding at an even faster pace. This shift in focus by established players towards AI-centric memory has, inadvertently, created a vacuum in the market for mainstream, high-volume DRAM components essential for personal computers, servers, smartphones, and embedded systems. These conventional electronics still demand vast quantities of reliable and affordable memory, a need that is increasingly underserved as leading manufacturers chase higher margins in the AI sector.
Furthermore, the memory market has historically been susceptible to pricing fluctuations and, at times, accusations of market manipulation. Legal challenges concerning alleged coordination among major suppliers have occasionally surfaced, underscoring the inherent volatility and strategic importance of this sector. Regardless of the outcomes of such cases, the fundamental engineering challenge persists: demand for memory, across all tiers, remains robust, and conventional electronics manufacturers are in constant need of affordable, readily available DRAM. This dynamic presents a golden opportunity for new entrants capable of scaling production.
CXMT’s Journey and China’s Semiconductor Ambitions: A Chronology
CXMT’s rise is a testament to China’s ambitious strategy to achieve self-reliance in critical semiconductor technologies. Founded in 2016, CXMT has rapidly progressed from initial research and development to commercial production. By 2019, the company had already commenced pilot production of 19nm-class DDR4 DRAM. This rapid advancement, achieved in a relatively short timeframe compared to the decades-long trajectories of its international competitors, underscores the significant state-backed investment and strategic focus placed on memory development within China.
The push for domestic semiconductor capabilities is a cornerstone of China’s "Made in China 2025" initiative and a critical component of its national security and economic strategy. China remains the world’s largest consumer of semiconductors, importing hundreds of billions of dollars worth of chips annually. This heavy reliance on foreign technology, particularly amidst escalating geopolitical tensions and export controls, has spurred immense investment in domestic alternatives. CXMT, alongside other Chinese semiconductor firms like Yangtze Memory Technologies Corp (YMTC) in NAND flash, is at the forefront of this national endeavor.

The development of advanced DRAM manufacturing processes by CXMT is not merely about market share; it is about building supply chain resilience and reducing China’s vulnerability to external pressures. By enhancing its domestic memory capabilities, China aims to secure a stable and reliable source of components for its vast electronics manufacturing ecosystem, encompassing everything from smartphones and automotive systems to industrial equipment and cloud infrastructure.
Implications for China’s Semiconductor Independence and Global Supply Chains
The successful mass production of LPDDR5X using a high-k metal-gate process by CXMT carries profound implications. First and foremost, it signifies a tangible reduction in China’s reliance on foreign memory manufacturers such as Samsung, SK Hynix, and Micron for increasingly advanced DRAM products. This lessens the impact of potential supply chain disruptions or geopolitical restrictions on critical components.
For Chinese electronics manufacturers, this development offers a larger, domestically sourced supply of memory. In a volatile global market, having a reliable local supplier can translate into greater supply security, potentially more stable pricing, and reduced lead times. This is particularly advantageous for companies operating in sectors deemed strategically important by Beijing, such as telecommunications (e.g., Huawei) and high-tech manufacturing.
Beyond national independence, CXMT’s progress could introduce a new dynamic into the global memory market. While established players continue to push the boundaries of technology for high-margin AI applications, CXMT is demonstrating its capability to address the massive and sustained demand for mainstream, high-performance memory. This strategic positioning could lead to a more diversified global supply chain, offering alternative sources for manufacturers worldwide.
Navigating the Competitive Arena: Mainstream vs. Cutting Edge
It is crucial to understand that CXMT does not necessarily need to immediately surpass the technological prowess of Samsung or SK Hynix at the absolute cutting edge to become a significant global player. The market is vast and segmented. While AI accelerators demand the fastest and most advanced HBM, a myriad of other devices – from everyday laptops and industrial control systems to automotive infotainment units and IoT devices – require reliable, cost-effective, and sufficiently performant DRAM. For these applications, factors such as price, availability, and consistent performance often outweigh the need for bleeding-edge speeds or extreme capacities.
This is precisely where companies like CXMT can carve out a substantial niche. If CXMT can consistently deliver reliable LPDDR5X and other mainstream DRAM products at competitive prices and in sufficient quantities, it presents a compelling value proposition for electronics manufacturers globally. The sheer scale of China’s domestic electronics industry provides CXMT with an immediate and enormous customer base. Chinese smartphone makers, PC manufacturers, and automotive companies can increasingly integrate locally manufactured memory into their products, thereby fostering economies of scale and enabling CXMT to further refine its processes and improve its technology.
Once Chinese memory components establish a track record of reliability, availability, and competitive pricing within the vast domestic market, international adoption becomes a more natural progression. As these components become integrated into established global supply chains, replacing them becomes considerably more challenging. Engineers qualify components, product designers build systems around them, distributors establish inventories, and long-term supplier relationships are forged. This entrenchment in the supply chain provides a robust competitive advantage that extends beyond mere price.
Challenges and the Path Forward
Despite this significant breakthrough, CXMT still faces substantial challenges. The "doubling of memory density" is an engineering achievement, but its commercial viability hinges on the ability to achieve high manufacturing yields at scale. Semiconductor manufacturing is notoriously complex, and achieving consistent, high-volume production with competitive yields often takes years of iterative refinement and optimization. Established players like Samsung, SK Hynix, and Micron possess decades of experience, enormous production capacities, and vast intellectual property portfolios that grant them a significant competitive edge across many advanced memory technologies.
Furthermore, geopolitical factors continue to loom large. The ongoing technology rivalry between the United States and China could lead to further export controls or restrictions on critical manufacturing equipment, software, or intellectual property that CXMT might require for future advancements. Gaining broader market acceptance outside of China will also require overcoming potential concerns regarding intellectual property, data security, and geopolitical alignments.
However, the trajectory is clear. If established memory manufacturers continue to heavily concentrate their investment and production on the high-margin AI market, and if Chinese manufacturers like CXMT consistently improve their ability to supply the mainstream electronics market with increasingly capable and cost-effective DRAM, then China is poised to capture an ever-more important share of the commercial memory market.
CXMT’s fifth-generation DRAM process, combining significantly higher density with the potential for competitive yields and pricing, could indeed usher in a new era for memory manufacturing over the next decade. This development positions China in a far stronger and more influential position within the global semiconductor supply chain than it has ever occupied before, signalling a potential realignment of power in one of the electronics industry’s most critical sectors. The implications extend beyond mere technological advancement, touching upon economic resilience, national security, and the future shape of global tech partnerships.